

Possible: Fast Cash & Credit
Possible Finance - A Public Benefit Corporation
- Ratings
- 4.4
- Installs
- 1,000,000+
- Category
- Finance
Possible: Fast Cash & Credit analysis by Appwee
When money is tight, the hardest part is often not finding a budgeting spreadsheet; it is handling one awkward gap between today’s expense and the next payday. Possible: Fast Cash & Credit is built around that moment. I looked at it as a finance app for short-term cash access and credit-building, and my overall impression is that it makes more sense as a carefully managed emergency tool than as a general-purpose household money manager.
The app is developed by Possible Finance - A Public Benefit Corporation and is free to install. Its store summary points to three jobs: getting cash quickly, building credit, and using flexible payments. Those aims sound simple, but they create very different expectations. Someone who needs a small bridge for an urgent bill is approaching it differently from someone trying to establish a long-term credit history. I would decide which of those goals matters most before creating an account.
It is listed in the Finance category, has an Everyone content rating, and has reached more than a million installs. The current release is version 2.5.0, with a minimum operating-system requirement of version 10. That combination makes it broadly approachable from a device perspective, although financial suitability is a separate question from whether a phone can run the app.
How Possible fits into a shared household
A realistic example is a couple sharing a tablet or occasionally using one another’s phone. One person notices that a utility payment is due before payday and opens Possible to investigate whether the app can help. The other person may later use the same device for completely unrelated tasks. That does not make the account a shared wallet. The important boundary is that the financial profile belongs to the individual who creates and uses it, not automatically to everyone in the home.
I would avoid treating the application like a family banking dashboard. It is not a convenient place to let several people browse one person’s borrowing activity, and I would not hand a logged-in finance app to a child just because the content rating is Everyone. The age label describes the app’s general content suitability; it does not turn borrowing into a family activity or remove the need for adult judgment.
On a shared device, my first practical rule would be simple: finish the session, sign out when appropriate, and do not leave sensitive account screens open. I would also keep conversations about repayment separate from casual household spending. If two adults are coordinating bills, they can agree who is responsible for a payment, but each person should understand whose account is being used and whose financial record may be affected.
This distinction is especially useful in households where one person normally handles money. Convenience can quietly become confusion if a partner assumes that an application opened on the family tablet is a joint account. Possible is better approached as an individual financial service that may be discussed within a household, not as a substitute for a shared current account or a joint budgeting app.
What the first setup should accomplish
During setup, I would slow down instead of applying for help automatically. Read each screen, check the repayment information shown for your situation, and make sure the personal details belong to the actual applicant. A rushed application made from someone else’s device can create avoidable problems, especially when household members have similar names or share contact information.
I would also decide in advance what the money is for. A necessary prescription, transport cost, or bill shortfall is easier to evaluate than vague spending money. Writing down the amount needed and the date income is expected can expose a problem early: if the next payment will not comfortably cover the repayment, the app is not solving the shortage; it is moving it closer to the next due date.
The most useful boundary is to treat available cash as a repayment decision, not as extra income. That mindset changes how I would use the app. I would not open it merely to see how much might be accessible, and I would not let another household member make that decision casually on my behalf. The convenience of a mobile application can make borrowing feel less serious than it is.
Possible is free to download, but “free” should not be read as “costless in every financial sense.” Before accepting anything, I would inspect the terms presented inside the application and consider the complete effect on my budget. The app’s price label tells me there is no purchase price for the download; it does not replace careful reading of any offer or repayment obligation.
Another setup tip is to keep the account holder’s information consistent. If a shared phone has several email accounts or payment tools attached to it, pause before selecting one. The right workflow is to use the applicant’s own details, review the destination and repayment arrangements carefully, and save a record of what was agreed. That record is valuable when a partner later asks why a payment is scheduled or how much room remains in the monthly budget.
Coordinating without turning one account into a household account
Possible can fit into household planning when the communication around it is clear. For example, one adult may use it to cover an urgent car expense while the other adjusts grocery spending until payday. That can be a reasonable coordination plan if both people know the amount, the repayment timing, and which regular bill will be reduced to make room.
What I would not do is let a partner apply from my profile or ask a teenager to manage the repayment because they happen to use the same phone. Shared responsibility should be discussed outside the app, while account actions remain with the person whose identity and finances are involved. This is not about distrust; it is about preventing a household conversation from being mistaken for formal account authority.
A small written plan helps. I would note the reason for using the service, the repayment date displayed in the account, and the household expense that must remain protected. Then I would check the plan against fixed commitments such as rent, food, transport, and utilities. If the repayment depends on skipping an essential bill, the safer choice is to look for a non-borrowing solution first.
For shared-device use, notifications and account access deserve attention too. I would not assume that a family member should see every alert simply because they use the same device. At the same time, I would not hide a repayment that affects joint household cash flow. The right balance is private account access with honest financial coordination.
This is one area where Possible differs from a traditional household budgeting app. A budget tool is usually designed to show categories, spending patterns, and shared planning. Possible is focused on an individual’s access to cash and credit-related activity. If your main goal is to coordinate several people’s bills, a dedicated household budget or bank-account arrangement may be a better fit. If the immediate issue is an individual shortfall and you understand the repayment, Possible has a more specific role.
Credit-building expectations and trust
The credit-building promise deserves a measured interpretation. Using a financial product associated with credit does not mean that every person will see the same result, and it should never be treated as a guaranteed shortcut to a strong credit profile. I would approach it as one part of a broader pattern of responsible money management, not as a replacement for paying existing obligations on time or correcting errors in a credit report.
Trust matters here because the app is handling a sensitive decision: whether taking cash now is sensible for the person using it. The 4.4 average rating from roughly 63,000 ratings and about 29,000 written reviews suggests that many people have found value in the service, but a crowd response cannot determine whether a particular repayment schedule fits your income. Reviews can help reveal common user experiences, while your own budget must make the final decision.
I would also separate trust in the developer from trust in my own plan. Possible Finance - A Public Benefit Corporation is clearly identified as the developer, which is useful when checking that the correct application is installed. Still, no developer name or rating should replace reading the actual terms presented during an application. Financial products require more attention than ordinary free utilities because an inconvenient repayment can affect the rest of the month.
For a household, the age context is straightforward but important. The Everyone rating means the app is not presented as containing mature entertainment content, yet borrowing should remain an adult responsibility. I would not encourage a minor to explore cash access, enter another person’s details, or make decisions about credit simply because the app appears in a general-purpose store.
With older children, the useful conversation is educational rather than operational. I might explain why a short-term advance still has to be repaid, how a due date competes with other bills, and why a credit score is not the same thing as available cash. Those lessons can happen without giving a child access to the account or asking them to coordinate sensitive financial information.
Where the app feels useful—and where it does not
The strongest use case is a temporary, clearly understood gap. If I knew an income payment was coming, had identified the essential expense, and could protect the repayment from ordinary bills, the app could be worth considering. The mobile format is convenient for someone who wants to review an option privately rather than visit a branch or make a long phone call.
It is less convincing as a routine way to stretch every pay cycle. Repeatedly borrowing for groceries, subscriptions, or ordinary discretionary purchases can signal that the underlying budget is too tight. In that situation, a conversation with a creditor, a payment-plan request, a community resource, or a slower spending reset may be more useful than another short-term advance.
I would also skip it if the main need is a shared account, long-term savings, investment management, or detailed expense tracking. Possible is not the tool I would choose for monitoring a family’s categories or building a joint emergency fund. A conventional bank account can be clearer for shared money, while a budgeting application can provide better visibility across household spending.
There is also a psychological trade-off. Fast access can reduce stress during a genuine emergency, but the same speed can encourage an impulsive decision. I would prefer an app that makes me pause and calculate rather than one that makes borrowing feel like a normal tap between shopping tasks. The most responsible workflow is to compare the repayment with the next month’s commitments before accepting anything.
Another non-obvious point is that credit-building and cash access should not be confused. A person might be interested in one but not need the other. If the priority is improving credit, I would examine the exact reporting and repayment implications shown in the account and compare them with other established credit-building choices. If the priority is emergency cash, I would compare the total burden and timing with alternatives such as a bank overdraft arrangement, employer advance, or negotiated bill extension where available.
My household verdict
After looking at Possible through the lens of individual use, shared devices, and household coordination, I see a focused finance app rather than a family money center. Its free installation, accessible age rating, and large user base make it easy to investigate, while the combination of cash access and credit-building gives it a clear purpose for people facing a short-term need.
My recommendation comes with a firm condition: use it only when the repayment is already mapped out. I would keep the account private, explain any household impact to the adults who share the budget, and never let a child or casual device user operate it. I would also compare the app with non-borrowing alternatives before accepting an offer, because speed is helpful only when it does not create a larger problem later.
For someone who needs a temporary bridge and can meet the repayment without sacrificing essentials, Possible may be a practical option to investigate. For someone looking for joint household banking, automatic family coordination, or a permanent fix for an income shortfall, I would choose a different kind of service. My final view is that Possible works best as a controlled emergency instrument, not as a default answer whenever the household budget feels uncomfortable.
If I were recommending it to a friend, I would say: install it only with a specific reason, review every term in your own account, and involve the household in the budget conversation without sharing account control. Used with those boundaries, Possible: Fast Cash & Credit can be useful for a narrow financial moment. Used casually or as a recurring supplement to income, it is much harder for me to recommend.
Gallery
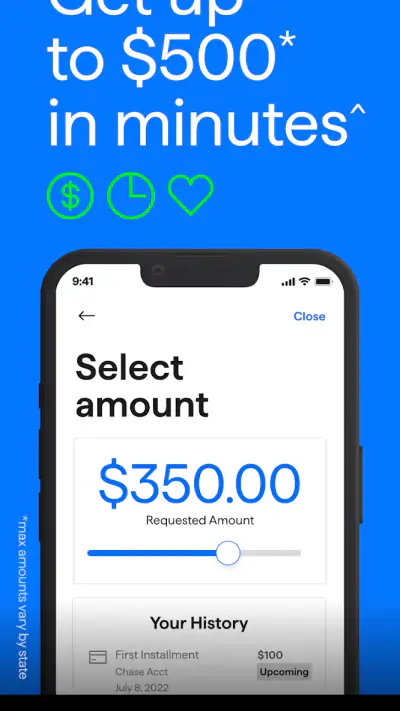
Possible: Fast Cash & Credit Pros and Cons
- Quick application process with minimal paperwork
- Clear repayment schedule helps users plan installments
- Useful for handling small
- unexpected expenses
- Mobile access makes account management convenient
- May offer loan options to users with limited credit history
- Interest and service fees can make borrowing expensive
- Approval and available amounts may vary by applicant
- Late payments could lead to additional charges
- Not available in every country or region
- Requires careful review of privacy and data-sharing terms
Possible: Fast Cash & Credit Frequently Asked Questions
What is Possible: Fast Cash & Credit?
Possible: Fast Cash & Credit is a mobile lending app designed to let eligible users apply for small-dollar personal loans directly from an Android or iOS device. The application process generally involves creating an account, providing personal and financial information, and allowing the service to review your eligibility. Approval, loan amounts, repayment schedules, and availability can vary depending on your location and individual profile.
How does the loan application process work in Possible?
After downloading Possible, users typically create an account, verify their identity, connect a bank account, and submit an application through the app. Possible then reviews the information provided and may display available loan terms before the user accepts an offer. You should carefully check the total repayment amount, payment dates, fees, and any other conditions before confirming the loan, since approval is not guaranteed.
Does Possible guarantee approval or work for everyone?
No. Possible does not guarantee that every applicant will be approved. Eligibility may depend on factors such as your state or country, age, identity verification, income, banking history, account activity, and other information assessed during the application. Even if you have used similar lending services before, the result can differ. Always review the current availability and eligibility requirements in the app.
How much does Possible cost, and what should borrowers check?
The cost of borrowing through Possible can vary according to the loan offer, location, repayment structure, and applicable disclosures. Before accepting an offer, review the annual percentage rate or equivalent cost information, finance charges, origination or other fees, the total amount due, and the payment schedule. Missing payments may also lead to additional consequences, so only borrow an amount you can repay.
Is Possible safe to use, and what information does it require?
Possible may request sensitive information such as your name, address, identification details, income information, and bank account data to verify your identity and assess an application. Use the official app store listing and confirm that the developer is legitimate before downloading. Read the privacy policy and permissions carefully, keep your login details secure, and avoid sharing account credentials with anyone claiming to offer unofficial assistance.














